Cautious Indian Markets Weekly View: Nifty, Bank Nifty and Sensex Outlook for Sept 21–25, 2026
Indian markets enter the September 21–25, 2026 week after completing their sixth consecutive weekly decline, the longest losing streak for the benchmarks since 2020.
Nifty 50 closed Friday at 23,346.40, Sensex ended at 74,294.96, while Bank Nifty finished at 56,358.70. Nifty lost 0.22% during the week and Sensex declined 0.65%. Bank Nifty also slipped about 0.44%. The weakness was relatively controlled compared with the previous week, but the broader trend is still corrective.
Friday did provide some relief. Nifty gained 0.33% as crude oil eased and bargain buying appeared after the recent correction. However, Reuters noted that the move looked more like buying after oversold conditions than a confirmed change in market sentiment.
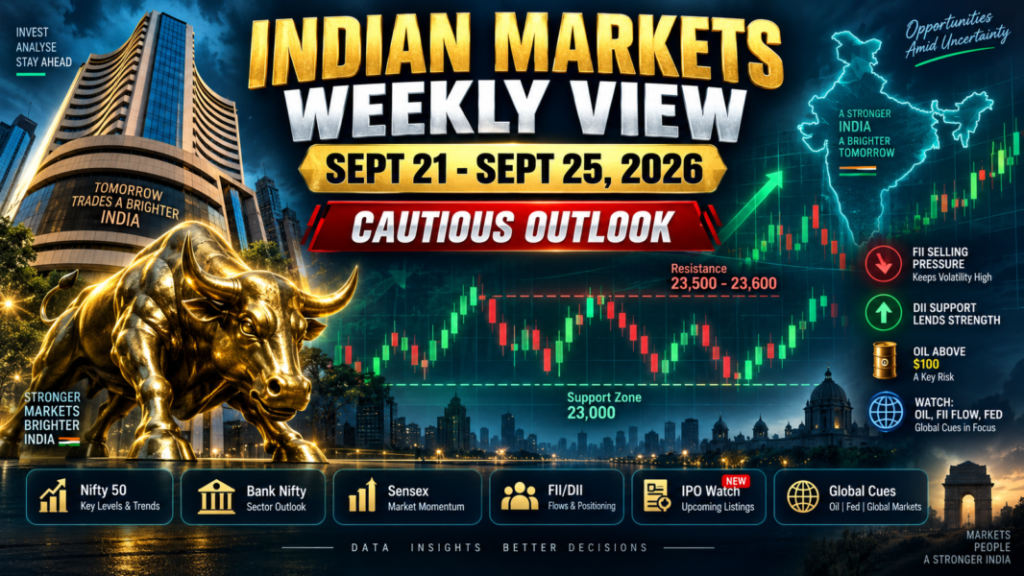
For this Indian Markets Weekly View, the setup for Sept 21–25 is therefore cautious and range-bound, with 23,000–23,100 acting as the most important support zone and 23,500–23,600 becoming the first major hurdle for a meaningful recovery.
📊 Indian Markets Weekly View: Latest Index Snapshot
| Index | Sept 18 Close | Important Support | Important Resistance |
|---|---|---|---|
| Nifty 50 | 23,346.40 | 23,000–23,100 | 23,500–23,600 |
| Bank Nifty | 56,358.70 | 55,800–56,000 | 56,900–57,200 |
| Sensex | 74,294.96 | 74,000 | 74,700–75,000 |
The weekly Nifty chart remains under pressure. The index is below its 20-week, 50-week and 100-week moving averages, while weekly RSI remains below 50. At the same time, India VIX fell 7.3% during the week to 11.39, suggesting that traders are not currently pricing in an extreme volatility event.
That combination often produces a market that moves sharply intraday but struggles to establish a sustained trend.
📈 Indian Markets Weekly View: Nifty 50 Weekly Levels
Nifty moved inside a roughly 477-point weekly range before ending at 23,346.40.
The most important technical feature is the support around 23,000–23,100, which corresponds with the recent swing-low zone. Technical analysts are treating 23,500 as the first resistance after the index recently slipped below it.
🎯 Nifty Support Levels
Immediate support sits around:
23,200–23,100
The stronger support area is:
23,050–23,000
If Nifty closes decisively below 23,000, attention may shift towards:
22,900–22,700
Economic Times technical analysis places immediate weekly supports at 23,100 and 22,930, with the 23,000 zone carrying particular importance for the broader structure.
🚧 Nifty Resistance Levels
The first recovery hurdle is:
23,500
Above this comes:
23,600
A sustained breakout could open room towards:
23,780–24,000
Moneycontrol also identifies 23,500–23,600 as the key resistance zone and 23,100–23,000 as the important support band.
📌 Expected Nifty Weekly Range
Base range: 23,000–23,600
Bullish extension: Above 23,600 → 23,800–24,000
Bearish extension: Below 23,000 → 22,800–22,700
Until one side of this range breaks with volume and market breadth, traders may continue to see stock-specific opportunities rather than a broad directional rally.
🏦 Bank Nifty Weekly Outlook
Bank Nifty ended Friday at 56,358.70, down roughly 0.44% for the week.
The banking index traded between about 55,795 and 56,994 last week. It recovered from the lower end of that range but failed to reclaim 57,000.
Bank Nifty Support and Resistance
| Zone | Level |
|---|---|
| Immediate support | 56,000 |
| Major support | 55,800–55,500 |
| Immediate resistance | 56,700–56,900 |
| Major resistance | 57,000–57,200 |
| Higher recovery area | 57,500–57,800 |
A move above 56,700–56,900 could improve short-term momentum.
The more important confirmation, however, would come only above 57,000–57,200.
On the downside, failure to hold 56,000 could expose the 55,800–55,500 region.
Moneycontrol identifies 57,000 as an important Bank Nifty level for the new week, while broader technical analysis places the banking index inside a consolidation phase.
For now, Bank Nifty looks range-bound rather than strongly bearish.
🔔 Sensex Weekly View
Sensex closed Friday at 74,294.96, almost unchanged for the session but down about 0.65% for the week.
The index traded as high as 74,728 on Friday but failed to retain the gains.
Sensex Levels to Watch
Immediate support: 74,000
Stronger support: 73,500–73,700
Immediate resistance: 74,700
Major resistance: 75,000–75,300
If Sensex can close above 75,000, the recovery could extend towards 75,700–76,000.
Below 74,000, however, traders may again start watching the lower 73,500 area.
Expected Sensex Weekly Range
73,700–75,300
This range should be treated as a working technical framework rather than a fixed prediction.
💰 FII and DII Overview: Last Week’s Institutional Activity
Foreign institutional selling remained one of the biggest challenges for the market.
| Date | FII Net ₹ Cr | DII Net ₹ Cr |
|---|---|---|
| Sept 15 | -2,977.86 | +2,686.05 |
| Sept 16 | -2,032.61 | +3,908.23 |
| Sept 17 | -3,208.76 | +3,617.75 |
| Sept 18 | +599.54 | +1,019.69 |
During the four trading sessions, FIIs were net sellers of about ₹7,620 crore, while DIIs were net buyers of roughly ₹11,232 crore.
Friday finally brought a small change: FIIs returned as net buyers of approximately ₹600 crore.
Domestic institutions, meanwhile, continued buying throughout the week.
This domestic support remains important. Without persistent DII buying, the six-week correction could have been significantly deeper.
For the new week, watch whether Friday’s FII buying develops into a trend or remains a one-session event.
📉 Open Interest and Put-Call Ratio
Derivatives positioning suggests the market remains balanced around current levels rather than heavily positioned for a one-way move.
Latest Nifty option data for the September 22 expiry showed:
Nifty spot: 23,346.40
PCR: 1.13
Max Pain: 23,350
Highest Call OI: 24,000
Highest Put OI: 23,300.
🔍 What Does the Nifty PCR Suggest?
A PCR of approximately 1.13 is close to neutral.
It indicates slightly more Put positioning than Call positioning but not enough to indicate an extreme.
The important strikes are more useful:
23,300: strong Put concentration
23,500–23,600: immediate trading hurdle
24,000: biggest Call OI wall
If Nifty holds 23,300 and Call writers unwind at higher strikes, short covering could help the index move towards 23,500–23,600.
If 23,300 Put writers start exiting and Nifty breaks 23,100, pressure could return quickly.
🏦 Bank Nifty Option Positioning
Bank Nifty option data showed:
PCR: 0.96
Max Pain: 57,200
Highest Call OI: 58,000
Highest Put OI: 57,500.
Remember that OI levels change throughout the trading day, especially near expiry. They should be rechecked live before taking any derivatives position.
🌍 Global Geopolitical News and Stock Market Impact
🛢️ Middle East Risk Remains the Main Oil Trigger
Crude remains the biggest external risk for Indian equities.
Brent crude ended Friday around $104.87 per barrel, while WTI settled near $100.30. Prices declined on Friday as fears around Saudi supply disruption eased, but Middle East shipping risks remain unresolved.
The Strait of Hormuz remains heavily disrupted, while tensions involving regional energy infrastructure continue to affect supply expectations.
For India, crude above $100 can influence several parts of the economy:
- Import costs rise.
- Inflation risk increases.
- The rupee faces additional pressure.
- Fuel-intensive industries see higher costs.
- Aviation, chemicals, paints and tyre companies can face margin pressure.
- Higher inflation can affect domestic interest-rate expectations.
A sustained fall in Brent below $100 would therefore be a meaningful positive for Indian markets.
🇺🇸 US Rates Remain Another Major Global Risk
The US Federal Reserve raised rates during the week to a 3.75%–4.00% range and indicated that more tightening may be required.
Higher US yields can reduce the relative attractiveness of emerging-market equities and make foreign investors more selective about India.
The US 10-year Treasury yield remains close to the psychologically important 5% level, which global investors will continue to monitor.
For India, the ideal combination would be:
Lower oil + softer US yields + a stable rupee.
That would reduce three major sources of pressure at the same time.
Global Markets Outlook: Fed, Oil Prices and Bond Yields in Focus
🌏 Important Global Events This Week
Markets will also track major US-China diplomatic discussions and the opening of the United Nations General Assembly.
Reuters notes that global investors will focus on trade, technology competition, Iran-related developments and wider geopolitical risk during the coming week.
These developments may affect technology stocks, commodities, currencies and overall risk sentiment.
Wall Street Week Ahead: Interest Rates, AI and Middle East Risks
🇷🇺 Russia Sanctions Risk and India
Another energy-related issue has emerged from proposed new US sanctions targeting countries that purchase significant volumes of Russian crude.
Reuters reports that the proposal could create additional uncertainty for India’s crude sourcing and trade relationship with the United States.
The direct market impact will depend on whether the proposal advances and what form any final measures take.
For investors, the important point is that India’s energy-import strategy could face additional uncertainty at a time when Middle East oil supplies are already disrupted.
🏛️ Latest SEBI Updates
SEBI released several market-structure updates during the week.
🖥️ Stronger Business Continuity and Disaster Recovery Rules
On September 15, SEBI released a consultation paper proposing measures to strengthen Business Continuity Plans and Disaster Recovery systems for Market Infrastructure Institutions such as exchanges and clearing organisations.
This is important because modern exchanges depend heavily on uninterrupted technology infrastructure.
Stronger disaster-recovery rules can improve resilience during system failures, cyber incidents or major operational disruptions.
Latest SEBI Update: Common Reporting Platform Extended to Clearing Corporation Members
🔄 Common Reporting Mechanism Extended
On September 17, SEBI announced that the Samuhik Prativedan Manch, a technology-based common reporting mechanism, had been extended to members of clearing corporations.
The broader objective is to simplify and standardise regulatory reporting.
📊 Closing Auction Review Still Relevant
SEBI’s September 12 consultation on the Closing Auction Session, market timings and derivatives settlement methodologies remains important for F&O traders.
The regulator is reviewing how expiry-day settlement prices should interact with closing-auction prices after unusual end-of-day volatility.
This is one of the most important market-structure topics for active derivatives traders.
🏷️ IPO Updates for Sept 21–25
The primary market remains extremely active.
The headline issue is the National Stock Exchange IPO.
The NSE IPO opened September 17 and closes on September 21, with a price band of ₹1,700–₹1,785 and an issue size of about ₹22,562 crore. Listing is scheduled for September 24.
NSE IPO Details: Price Band, Dates and Listing Schedule
📅 IPO Calendar
| IPO | Subscription Dates | Price Band |
|---|---|---|
| NSE | Sept 17–21 | ₹1,700–₹1,785 |
| Sonaselection | Sept 17–21 | ₹94–₹99 |
| Varmora Granito | Sept 22–24 | ₹140–₹148 |
| Vivekanand Cotspin | Sept 21–23 | ₹32–₹37 |
| FX Multitech | Sept 21–23 | ₹110–₹116 |
Several IPOs from the previous week are also listing during Sept 21–25, including Hero Motors, Jindal Supreme, SS Retail and NSE.
IPO demand remains strong, but investors should continue checking:
valuation, profitability, debt, cash flows, offer-for-sale component and use of fresh proceeds.
A heavily subscribed issue is not automatically a good long-term investment.
Latest IPO Updates: NSE IPO and Upcoming Indian IPOs
🪙 Commodity Market Weekly View
🛢️ Crude Oil
Brent finished Friday close to $104.87, while WTI closed around $100.30.
For India, the following crude zones are worth watching:
Below $100: meaningful relief
$100–$105: elevated but manageable
$105–$110: increasing inflation pressure
Above $110: serious macro concern
Oil has become the single most important commodity indicator for Indian equity sentiment.
🥇 Gold
Gold ended Friday around $4,390 per ounce, rising roughly 1.2% during the session and recording its first weekly gain in four weeks.
The decline in crude prices helped reduce inflation fears, encouraging investors to unwind some bearish gold positions.
However, higher US rates remain a headwind.
Gold therefore remains caught between:
Safe-haven demand from geopolitical uncertainty
and
Higher opportunity cost from rising interest rates.
That could keep prices volatile.
🥈 Silver
Silver rose roughly 2.3% on Friday to around $66.70 per ounce and was also heading for a weekly gain.
Silver can move more aggressively than gold because it responds both to precious-metal demand and industrial activity.
Investors using silver for diversification should therefore expect larger price swings.
💱 Currency Update: USD/INR
The Indian rupee closed Friday at approximately ₹95.875 per US dollar, losing about 0.3% during the week.
The currency briefly weakened beyond ₹96 during the week before recovering, with traders reporting probable RBI intervention.
The ₹96 level is becoming an important psychological line.
USD/INR Weekly Watch
Support for rupee: ₹95.20–₹95.40
Immediate dollar resistance: ₹96.00
Higher risk zone: ₹96.20–₹96.50
Rupee movement this week will mainly depend on:
crude oil, US bond yields, foreign flows and RBI intervention.
A fall in oil could help the rupee recover.
🚀 Two Stocks That Performed Well Last Week
1. HDFC Life Insurance
HDFC Life was the best-performing Nifty 50 stock last week, gaining approximately 4%.
Insurance stocks benefited from investor optimism around industry growth and improved transparency associated with new financial-reporting standards.
The stock also stood out because it generated positive returns during a sixth consecutive weak week for Nifty.
That relative strength makes it a stock worth monitoring, although one week’s performance alone should never be treated as a buy signal.
2. HCL Technologies
HCL Technologies gained approximately 3.6% for the week, making it another major Nifty outperformer.
This performance is interesting because broader technology sentiment remains sensitive to US bond yields and interest rates.
Investors tracking HCL Tech should therefore watch:
US technology spending, deal wins, currency movement and global rate expectations.
🏭 Two Strong Sectors Last Week
📺 Media
Nifty Media was the strongest major sector, gaining around 1.1% during the week.
The move came even as most broader indices declined.
Sector leadership can change quickly, so investors should distinguish between short-term momentum and long-term business fundamentals.
🛒 FMCG
Nifty FMCG gained around 0.9%, making it another outperforming sector.
FMCG often attracts defensive interest when global macro uncertainty increases.
The sector may remain comparatively resilient if oil volatility and higher rates continue to hurt cyclical areas.
Pharma and metals also ended the week higher, gaining around 0.7% and 0.4% respectively.
⏳ Short-Term Market Approach
Short-term traders should remain selective rather than assuming that six weak weeks automatically mean a large rebound is due.
The cleaner framework is to watch 23,000–23,100 support and 23,500–23,600 resistance on Nifty.
Until either side breaks, position sizes should remain controlled.
Areas showing comparatively better relative strength include media, FMCG, selected pharma names and some individual financial stocks.
Avoid chasing stocks after unusually large one-day moves, particularly in a market where global headlines can quickly reverse sentiment.
🌱 Long-Term Investment Approach
For long-term investors, the six-week correction can be used as an opportunity to review valuations rather than to react emotionally to index movements.
The focus should remain on companies with:
- Consistent earnings growth
- Healthy cash flow
- Manageable debt
- Strong return ratios
- Durable competitive advantages
- Reasonable valuations
Staggered investing can reduce timing risk when global rates and energy prices remain uncertain.
Large banks, healthcare, selected technology leaders, consumer businesses, industrials and diversified index funds can remain areas to research depending on individual goals and risk tolerance.
The key distinction is simple: a falling share price does not automatically make a stock cheap.
🎯 Indian Markets Weekly View: Final Weekly Range Forecast
For September 21–25, the Indian market enters another important week.
Nifty’s crucial zone is:
23,000–23,100 support
against
23,500–23,600 resistance.
A sustained breakout above 23,600 could improve the setup towards 23,800–24,000.
A decisive break below 23,000 may expose 22,800–22,700.
For Bank Nifty:
Support: 55,800–56,000
Resistance: 56,900–57,200
Higher recovery zone: 57,500–57,800.
For Sensex:
Support: around 74,000
Resistance: 74,700–75,000
Broader working range: approximately 73,500–75,300.
Four factors deserve the most attention this week:
Crude oil, because Brent remains above $100.
US bond yields, following the Federal Reserve’s rate increase.
FII activity, after roughly ₹7,620 crore of net foreign selling last week.
And the 23,000 Nifty support zone, because a decisive breakdown would materially weaken the current technical structure.
This is therefore a market where patience and stock selection matter more than predicting a dramatic index move.
❓ Frequently Asked Questions
Q1. What is the Nifty outlook for Sept 21–25, 2026?
Nifty remains in a corrective, range-bound structure. The key support lies around 23,000–23,100, while 23,500–23,600 is the first significant resistance. Above 23,600, the index could attempt 23,800–24,000.
Q2. What are the important Bank Nifty levels this week?
Bank Nifty closed at 56,358.70. Support is around 56,000 and 55,800, while resistance is around 56,900–57,200. A sustained move above 57,200 would improve short-term momentum.
Q3. What is the latest Nifty put-call ratio?
The Nifty PCR for the September 22 expiry stood around 1.13 at Friday’s close. Max pain was around 23,350, with the highest Call OI at 24,000 and highest Put OI near 23,300.
Q4. Were FIIs buyers or sellers last week?
FIIs were net sellers of approximately ₹7,620 crore across the four trading sessions from Sept 15–18. DIIs were net buyers of roughly ₹11,232 crore during the same period.
Q5. What is the biggest risk for Indian markets this week?
The largest immediate macro risk remains crude oil above $100 combined with elevated global interest rates. Higher oil can affect inflation and the rupee, while high US bond yields can keep foreign flows under pressure.
Further Reading
Cautious Indian Markets Weekly View Sept 15–18, 2026
Strategy #2 – 20 EMA and 50 EMA Trend Trading Strategy for Beginners
Strategy #1 – Support and Resistance Breakout Strategy for Beginners
Stock Market 101 Lesson 39: ELSS vs PPF vs NPS – Ultimate Beginner Guide
Large-Cap vs Mid-Cap vs Small-Cap Mutual Funds
Rupee Fall 2026 Explained: Why INR May Stay Weak Against Dollar
⚠️ Disclaimer
This article is for educational and informational purposes only. It is not investment, trading, IPO, commodity, currency or financial advice. Support, resistance and weekly ranges are technical observations based on market information available through September 20, 2026 and may change after markets reopen. Stocks and sectors mentioned are examples for market analysis and are not buy or sell recommendations. Investors should conduct independent research and consult a SEBI-registered investment adviser before making financial decisions. Equity, derivatives, IPO, commodity and currency investments involve market risk, including possible loss of capital.
Article Information
Author: Kartalks Research Desk
Reviewed by: Kartalks Editorial Team
Content Type: Weekly Indian stock market outlook, Nifty 50 levels, Bank Nifty levels, Sensex view, support and resistance levels, FII/DII activity, sector performance, IPO updates, commodity trends, currency movement, global cues, and investor education
Sources: NSE, BSE, SEBI, weekly market data, FII/DII activity, sector performance data, IPO filings, commodity market data, currency market updates, company filings, and official public sources
Last Updated: September 20, 2026
Very detailed info on major indices, will be profitable if used the info properly.
Thank you.
Thank you for your feedback! We’re glad you found the detailed coverage of major indices useful. Wishing you informed and disciplined trading.