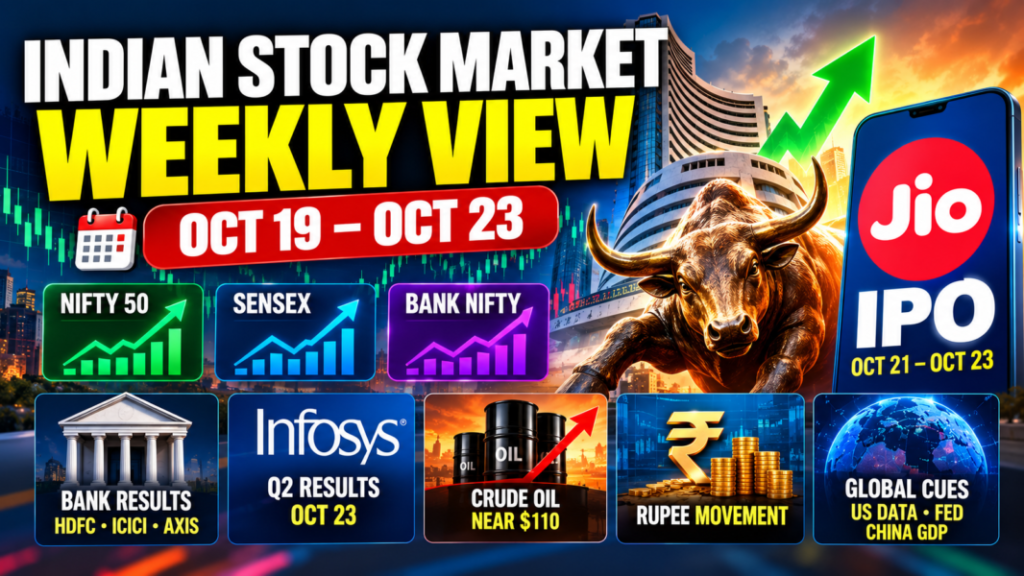
Indian Stock Market Weekly View: Jio IPO, Bank Results & Infosys Q2 in Focus | Oct 19–23, 2026
Indian equities head into the Dussehra-shortened week with something they have not had for a while — genuine upward momentum.
Nifty 50 gained nearly 2.8% last week, while Sensex rose more than 3%. IT stocks were at the centre of the recovery, recording their strongest weekly jump in 18 years after a string of better-than-feared quarterly results.
The mood has improved, but the next test starts immediately. HDFC Bank, ICICI Bank and Axis Bank reported their numbers over the weekend. Jio Platforms launches India’s biggest-ever IPO this week. Infosys reports on Friday.
At the same time, Brent crude has climbed close to $110 a barrel and Indian inflation is running hotter. That keeps this rally from becoming a simple one-way story.
Week Gone By – Indian Market Recap
| Index | Oct 16 Close | Weekly Change |
|---|---|---|
| Nifty 50 | 23,146.15 | +2.8% |
| Sensex | 74,729.27 | +3.1% |
| Bank Nifty | 55,844.00 | +1.1% |
Nifty moved between 22,288.45 and 23,149.85 during the week and finished almost at its weekly high.
That matters.
The market had spent several weeks struggling with foreign selling, expensive crude, a weak rupee and rising bond yields. Last week buyers finally found a reason to return: corporate earnings.
HCLTech, TCS, Wipro and Tech Mahindra helped revive interest in IT shares. Nifty IT surged 11.7% for the week, its biggest weekly rise in 18 years. TCS, Infosys, HCLTech and Tech Mahindra gained between 13.4% and 18.2%.
The rally was still concentrated in larger companies. Mid-caps rose only modestly, while the broader small-cap space failed to match the headline indices.
Inflation provided the less comfortable part of the story. India’s September retail inflation rose to 5.54%, up from 4.83% in August, while food inflation climbed to 7.74%. Wholesale inflation also accelerated sharply to 11.39%.
That means earnings helped stocks last week, but inflation and interest rates have not gone away.
Sector Performance: IT Steals the Show
IT was easily the standout sector.
Nifty IT gained 11.7%, helped by Q2 earnings, deal wins and some relief after the steep correction seen earlier. HCLTech’s results were particularly well received.
Auto also had a decent week, rising roughly 3.6%, while Realty gained around 2.7%. Oil & Gas advanced as energy prices stayed firm.
The weaker side of the market included Healthcare, Pharma, FMCG and PSU Banks. Nifty Healthcare lost about 1.1% during the week, showing that the rally was far from uniform.
For the week ahead, IT’s big run itself becomes a risk. After an 11%–12% weekly rise, good results may already be partly reflected in prices. Infosys on October 23 will therefore have to deliver more than just acceptable numbers.
FII & DII Activity
Foreign investors remained net sellers during the week despite Friday’s turnaround.
| Institutional Flow | Oct 12–16 | Oct 16 Alone |
|---|---|---|
| FII/FPI Cash | -₹8,990.5 crore | +₹1,165.9 crore |
| DII Cash | +₹7,812.8 crore | -₹3,661.3 crore |
The interesting part came on Friday.
FIIs turned net buyers for the session after persistent selling, while domestic institutions booked some profits. Exchange cash-market data show FIIs sold nearly ₹9,000 crore for the full week and DIIs absorbed most of it.
One positive FII session does not establish a new trend. Still, if foreign selling continues to ease while earnings remain supportive, one important source of pressure on Indian equities would weaken.
Global Market Recap
US Markets
Indian IT stocks rallied, but the global technology picture became more complicated.
Wall Street suffered another technology-led sell-off as investors questioned the amount of debt being used to fund the AI infrastructure boom.
The S&P 500 and Nasdaq finished the week lower, while the Dow managed a weekly gain. High borrowing costs and concerns around AI-related capital spending were the main pressure points.
US inflation also came in hotter than expected.
Markets currently assign a much higher probability to the Federal Reserve holding rates at its October meeting, but December rate expectations remain sensitive to inflation. The US 10-year Treasury yield finished Friday around 5.09%.
That matters for India because high US yields can draw money away from emerging markets.
Read the weekly market recap on Reuters
Europe and Asia
European equities recovered late in the week, with the STOXX 600 and FTSE 100 ending the week higher.
Asian markets were more uneven. Technology-heavy markets were vulnerable to the global AI sell-off, while higher energy prices remained another concern for oil-importing economies.
China also returns to focus this week. A Reuters poll expects third-quarter Chinese GDP growth of around 4.4% year-on-year, making China’s growth data relevant for metals, commodities and Asian equities.
Commodity & Currency Watch
Oil is probably the biggest macro risk facing Indian equities right now.
Brent crude settled at $109.86 a barrel on October 16, up 4.9% for the week.
WTI crude finished at $101.41, jumping 10.4% for the week.
Supply fears linked to tensions in the Middle East and risks to Russian energy infrastructure drove the move.
For India, $110 Brent is uncomfortable. It can increase the import bill, worsen the trade balance and add another layer of inflation pressure.
Gold ended around $4,165 an ounce, losing roughly 0.7% during the week. Silver slipped to around $57.05 an ounce and also ended lower.
The rupee provided better news.
USD/INR ended Friday around ₹94.96, with the rupee gaining roughly 2% during the week — its best weekly performance in seven months. RBI measures to reduce oil-company dollar demand helped.
The US Dollar Index closed near 101.87, down about 0.35% for the week.
Technical Outlook for Oct 19–23
These are technical reference zones based on recent price action and derivatives positioning. They are not guaranteed targets.
| Index | Support | Resistance |
|---|---|---|
| Nifty 50 | 23,000–22,900; 22,800 | 23,200–23,300; 23,500 |
| Bank Nifty | 55,500; 55,000 | 56,000; 56,500 |
| Sensex | 74,000; 73,000 | 75,000; 76,000 |
Nifty 50
Nifty finished at 23,146.15, close to Friday’s high.
The short-term picture has improved because the index reclaimed 23,000 and moved above its short-term averages.
The immediate test lies around 23,200–23,300. A sustained breakout could allow the recovery to stretch toward 23,500.
The first support sits around 23,000–22,900. A break below 22,800 would make the recent rebound look less convincing.
Bank Nifty
Bank Nifty closed at 55,844 and now faces an interesting Monday because HDFC Bank, ICICI Bank and Axis Bank announced results after Friday’s close.
The derivatives structure shows heavy resistance around 56,000, while 55,500 and 55,000 form the important support zones.
A sustained move above 56,000–56,200 would strengthen the banking setup. Below 55,000, the chart would turn weaker again.
Sensex
Sensex closed at 74,729.27.
The psychological 75,000 area is the first hurdle. Sustaining above it could open room toward 76,000.
Support sits around 74,000, followed by the 73,000 region.
India VIX & Derivatives Positioning
India VIX ended October 16 near 14.06, down roughly 2.2% from the previous week’s closing level.
The message is fairly simple: traders are no longer pricing the same degree of immediate fear seen earlier in October, but volatility has not disappeared.
Bank Nifty’s October derivatives series shows a Put-Call Ratio near 1.06, with heavy put interest around 55,000 and strong call interest near 56,000. That fits neatly with the technical range.
For Nifty, the options market also shows stronger put writing below the current price, although positioning can change rapidly after Monday’s opening and the holiday break.
Big Events to Watch This Week
| Date | Event | Market Relevance |
|---|---|---|
| Oct 19 | HDFC/ICICI/Axis reaction; UltraTech & Bajaj Finance results; Jio anchor book | Banks, cement, NBFCs |
| Oct 20 | NSE/BSE closed – Dussehra | No regular equity trading |
| Oct 21 | Jio Platforms & Paras Healthcare IPOs open | Reliance, telecom, primary market |
| Oct 22 | Major Q2 earnings continue | Stock-specific volatility |
| Oct 23 | Infosys Q2 results; Jio & Paras IPOs close | IT and primary market |
The exchange holiday is confirmed for Tuesday, October 20, for Dussehra.
UltraTech Cement, Bajaj Finance and Union Bank of India are among companies scheduled to report on October 19.
Infosys will present its September-quarter results to its board on October 23, according to the company’s official filing.
IPO Watch: Jio Takes Centre Stage
There is little doubt about the biggest primary-market story this week.
Jio Platforms’ IPO opens on October 21 and closes October 23. Anchor bidding takes place on October 19.
The price band has been fixed at ₹1,065–₹1,119 per share, with Jio offering 270 million new shares and seeking to raise as much as $3.2 billion. At the upper end, the issue values the company at about $108.3 billion.
The size of the offer means Reliance Industries and telecom stocks could receive additional attention.
Paras Healthcare also opens on October 21 and closes October 23. Its ₹1,450 crore mainboard IPO carries a price band of ₹660–₹693 per share.
HD Fire Protect is scheduled to list on October 21.
Grey-market premiums are deliberately excluded here because they are unofficial and can change quickly.
Read the Jio IPO details on Reuter
Stocks and Sectors to Watch
Private Banks
Monday could be particularly active for banking shares.
ICICI Bank reported a 20.1% rise in Q2 profit to ₹14,843 crore, beating estimates. Net interest income grew 17.7%, though its margin eased to 4.18%.
HDFC Bank’s profit increased 4.7% to ₹19,510 crore, narrowly missing expectations, while loans and deposits still grew at healthy double-digit rates.
Axis Bank profit rose 37.6% to ₹7,003 crore but fell slightly short of estimates because of higher costs.
How the market interprets margins may matter more than headline profit growth.
IT
The sector has already risen 11.7% in a week.
Infosys results on Friday now become the next major test. The market will look at large deal wins, AI-led revenue, margins and FY27 guidance rather than merely the profit number.
Reliance Industries
Jio’s IPO opens Wednesday.
The offering may provide a fresh valuation benchmark for Reliance’s digital business and could keep the parent company’s shares active throughout the week.
Oil-Sensitive Sectors
Airlines, paints, chemicals and other crude-dependent industries face a tougher cost environment with Brent near $110.
Two Growth Stocks to Study
These are companies worth researching, not buy recommendations.
1. HCLTech
HCLTech is one of India’s largest technology-services companies, with exposure to IT services, engineering, cloud, software and increasingly AI-led contracts.
Its Q2 profit rose 21.2% year-on-year to ₹5,132 crore, while revenue increased 11.5% to ₹35,620 crore. New deal wins reached $3.26 billion, and advanced AI annualised revenue climbed to $219 million. EBIT margin improved to 18.2%.
The stock closed at ₹1,380 on October 16 after a very strong earnings-driven rally.
From a chart perspective, ₹1,330–1,350 is an initial support region, while ₹1,385–1,400 is the first hurdle.
Key risk: the stock has already rerated sharply, while management still describes the demand environment as volatile.
What to monitor: deal conversion, AI revenue, margins and whether FY27 growth guidance improves.
2. ICICI Bank
ICICI Bank combines retail lending, corporate banking, cards, digital banking and financial-services subsidiaries.
Its latest Q2 numbers were strong: profit rose 20.1%, loans grew 30% and deposits increased 27.1%. Gross NPA improved to 1.20%.
The stock closed Friday at ₹1,396.80, before the weekend results were announced.
The ₹1,360–1,340 area is the first technical support reference. ₹1,400 is the immediate resistance, followed by the previous 52-week high region near ₹1,480.
Key risk: net interest margins are already narrowing, and another RBI rate increase could change funding and lending economics.
What to monitor: Monday’s reaction, NIM, deposit growth, credit costs and asset quality.
Read the ICICI Bank Q2 report on Reuters
Short-Term Market Setup
Nifty enters Monday with 23,000–23,300 as the immediate decision zone.
Bank Nifty has an equally clear battle around 55,500–56,000.
The positive trigger would be a combination of supportive bank earnings, a Nifty breakout above 23,300 and some continuation of Friday’s FII buying.
The main downside risk is crude oil. If Brent pushes decisively above $110 while US yields rise again, the rupee and Indian equities could quickly lose some of last week’s comfort.
The Tuesday holiday also means traders should account for overnight global risk before carrying short-term positions.
Long-Term Investor View
For long-term investors, last week’s rebound should not change the process.
India still has healthy economic growth and several sectors continue to produce solid earnings. Banks have improved their asset quality, telecom remains a structural growth story, and businesses linked to manufacturing, defence, digital services and financialisation continue to offer long-term themes.
But valuations matter.
Expensive crude, inflation above the RBI’s target, higher interest rates and elevated global bond yields can reduce the price investors are willing to pay for future earnings.
Instead of chasing a stock after a sharp weekly rally, long-term investors can use earnings season to compare revenue growth, margins, debt, cash generation and valuation.
Volatility becomes useful when it allows a good business to be studied at a more sensible price.
Indian Stock Market Weekly View: Next Week – 5 Key Things to Watch
- Private banks on Monday: ICICI Bank’s strong numbers face HDFC Bank and Axis Bank’s more mixed results.
- Nifty 23,300: a clean breakout would strengthen the short-term recovery.
- Jio Platforms IPO: India’s biggest IPO opens October 21 and could dominate primary-market attention.
- Infosys on October 23: the result will test whether IT’s 11.7% weekly surge has enough earnings support.
- Brent crude near $110: another oil spike is the clearest macro risk for inflation, the rupee and Indian equities.
FAQs
Q1. Is Nifty bullish for October 19–23?
The short-term trend has improved after Nifty reclaimed 23,000. A sustained move above 23,200–23,300 would strengthen the bullish setup. Falling below 22,900–22,800 would weaken it again.
Q2. Is the Indian stock market open on October 20?
No. NSE and BSE are closed for regular equity trading on Tuesday, October 20, 2026, for Dussehra.
Q3. What is the biggest event for the Indian market this week?
There is no single event. Bank earnings will drive Monday, Jio’s IPO opens Wednesday, and Infosys results arrive Friday. Crude oil remains the main global risk running through the entire week.
Q4. Why is $110 Brent crude a concern for India?
India imports most of its crude oil. Higher prices can increase the import bill, put pressure on the rupee and feed into transport, manufacturing and consumer inflation.
Q5. Can IT stocks continue rallying after gaining nearly 12% in a week?
They can, but the easy part of the rebound may already have happened. Further gains will increasingly depend on earnings, deal wins, guidance and whether global technology stocks stabilise. Infosys results on October 23 provide the next major checkpoint.
Further Reading
Indian Markets Weekly View: CPI, IT Earnings & Nifty Levels to Watch | Oct 12–16, 2026
Trading Strategy 101 – Lesson 6: Moving Average Pullback Strategy
Trading Strategy 101 – Lesson 5: RSI + Price Action Trading Strategy
Stock Market 101 – Lesson 37: Mutual Fund Mistakes
Stock Market 101 Lesson 39: ELSS vs PPF vs NPS – Ultimate Beginner Guide
Article Information
Author: Kartalks Research Desk
Reviewed by: Kartalks Editorial Team
Content Type: Weekly Indian stock market outlook, Nifty 50 levels, Bank Nifty levels, Sensex view, support and resistance levels, FII/DII activity, sector performance, IPO updates, commodity trends, currency movement, global cues, and investor education
Sources: NSE, BSE, SEBI, weekly market data, FII/DII activity, sector performance data, IPO filings, commodity market data, currency market updates, company filings, and official public sources
Last Updated: October 18, 2026
Disclaimer
This article is for educational and informational purposes only. It does not constitute investment advice or a recommendation to buy or sell securities. Market investments involve risk. Readers should conduct their own research and, where appropriate, consult a SEBI-registered investment adviser before making investment decisions.