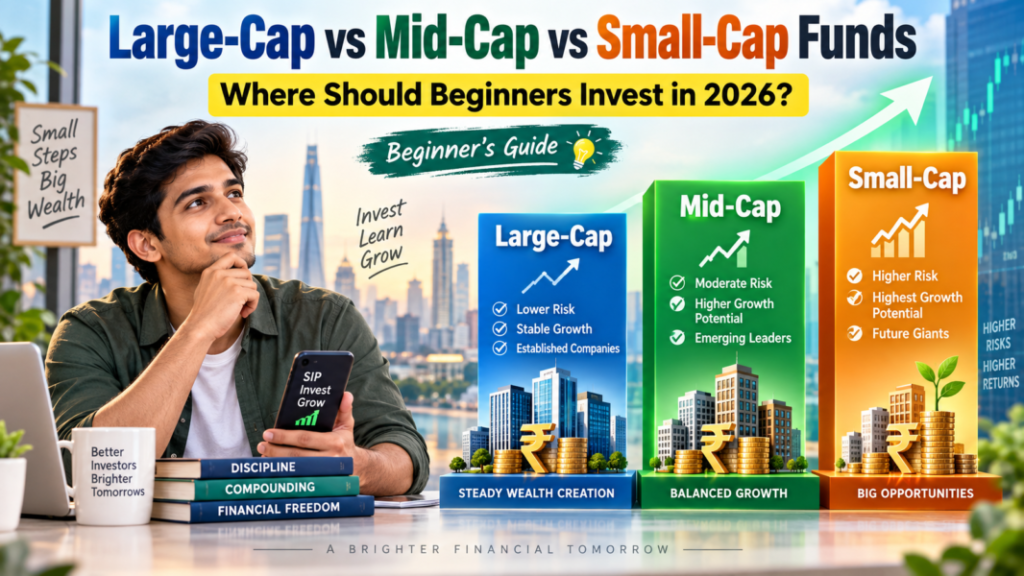
Large-Cap vs Mid-Cap vs Small-Cap Mutual Funds: Where Should Beginners Invest in 2026?
Choosing your first mutual fund can become confusing very quickly.
You open a mutual fund app and see large-cap funds, mid-cap funds, small-cap funds, flexi-cap funds, index funds and dozens of schemes under each category. Then you notice that one small-cap fund has delivered much higher past returns than a large-cap fund.
The natural thought is: why not simply invest in the fund giving the highest return?
That is where many beginners make their first mistake.
Large-cap, mid-cap and small-cap funds invest in very different types of companies. Their return potential is different, but so is the amount of risk you may have to tolerate.
For someone starting mutual fund investing in 2026, understanding this difference is more useful than searching for last year’s best-performing fund.
What Do Large-Cap, Mid-Cap and Small-Cap Actually Mean?
Companies listed on the stock market are commonly grouped according to their market capitalisation, or market cap.
In simple terms:
Market capitalisation = Share price × Total outstanding shares
A company with a very high market value falls into the large-cap group, while smaller listed companies fall into the mid-cap or small-cap groups.
Under SEBI’s current classification, large-cap companies are ranked 1st to 100th by full market capitalisation, mid-cap companies are ranked 101st to 250th, and companies ranked 251st onwards fall under small-cap. AMFI prepares the applicable stock list used by mutual funds.
| Category | Company ranking | General nature |
|---|---|---|
| Large-cap | 1st to 100th | Large, established businesses |
| Mid-cap | 101st to 250th | Growing medium-sized companies |
| Small-cap | 251st onwards | Smaller businesses with higher growth potential and risk |
The size of a company does not tell you whether the stock will give good or bad returns. It mainly helps us understand the type of business and the level of risk involved.
SEBI Mutual Fund Categorisation Rules
What Is a Large-Cap Mutual Fund?
A large-cap mutual fund mainly invests in India’s biggest listed companies.
Under the current SEBI framework, a large-cap fund must invest at least 80% of its assets in large-cap companies.
These companies are generally established businesses with recognised brands, larger revenues and relatively stronger access to capital.
Think of sectors such as banking, IT, consumer goods, energy, automobiles and pharmaceuticals. Many of India’s biggest companies fall into the large-cap universe.
Why Beginners Often Start With Large-Cap Funds
Large-cap funds can still fall sharply when the stock market corrects. They are not safe like an FD.
But compared with mid-cap and small-cap funds, their portfolios generally tend to be less volatile.
This makes them easier for a new investor to handle emotionally.
A beginner seeing their ₹1 lakh investment temporarily fall to ₹90,000 may remain invested. Seeing the same investment fall much further can lead to panic selling.
That behaviour matters just as much as fund selection.
AMFI Large-Cap, Mid-Cap and Small-Cap Classification
Large-Cap Funds May Suit Investors Who
- Are investing in equity for the first time
- Want relatively lower volatility within equity funds
- Have a long-term goal
- Prefer established businesses
- Do not want a very aggressive portfolio
A holding period of at least five years is a more sensible starting point for equity investing, though longer is usually better.
What Is a Mid-Cap Mutual Fund?
Mid-cap funds invest mainly in companies that sit below India’s 100 largest listed businesses.
SEBI requires a mid-cap fund to maintain at least 65% of its assets in mid-cap companies.
This is an interesting part of the market.
Some mid-sized companies have already built successful businesses but may still have plenty of room to expand.
A company that is mid-cap today could eventually become a large-cap company if its business keeps growing.
That growth opportunity attracts investors.
But there is a catch.
Mid-cap shares can move much more sharply than large-cap shares when market sentiment changes.
Why Mid-Cap Funds Can Deliver Higher Growth
Imagine two companies.
Company A is already one of India’s largest businesses. Doubling its revenue from ₹1 lakh crore to ₹2 lakh crore is not easy.
Company B is much smaller. Growing from ₹5,000 crore to ₹10,000 crore may be possible if its industry expands and management executes well.
That is one reason investors look towards mid-cap businesses for long-term growth.
But faster growth expectations also mean investors may pay high valuations for these companies. If earnings disappoint, their share prices can correct sharply.
For beginners, mid-cap funds usually work better as an addition to a core portfolio, rather than the entire portfolio.
A seven-year or longer investment horizon is a practical way to approach this category.
SEBI Guide to Understanding Mutual Funds
What Is a Small-Cap Mutual Fund?
Small-cap funds invest mainly in companies ranked below the top 250 by market capitalisation.
SEBI requires these schemes to invest at least 65% of their assets in small-cap companies.
This category often attracts attention after a strong stock-market rally because some small-cap funds can show very impressive historical returns.
But past returns tell only half the story.
Small companies may grow faster, but they can also face problems that larger businesses handle more easily.
These may include weaker balance sheets, limited access to funding, dependence on a few customers, lower trading liquidity or greater impact from an economic slowdown.
Small-Cap Returns Come With Bigger Ups and Downs
Suppose the stock market falls 10%.
That does not mean every category will fall exactly 10%.
During difficult market phases, small-cap stocks can sometimes fall much more than large companies. Recovery can also take time.
An investor who enters a small-cap fund expecting quick returns may struggle when the portfolio stays negative for one or two years.
That is why small-cap investing requires patience.
For long-term investors, a planning horizon of seven to ten years or more makes more sense than treating small-cap funds as a short-term return opportunity.
Large-Cap vs Mid-Cap vs Small-Cap Mutual Funds: Quick Comparison
| Factor | Large-Cap | Mid-Cap / Small-Cap |
|---|---|---|
| Risk | Relatively lower | Higher to very high |
| Return potential | Moderate to high | Higher potential, less predictable |
| Suitable role | Core portfolio | Additional growth allocation |
| Beginner friendly? | Generally yes | Mid-cap: limited exposure; Small-cap: cautiously |
| Suggested mindset | Stability + growth | Long-term growth + patience |
These are broad characteristics, not guaranteed outcomes. A large-cap fund can underperform and a small-cap fund can perform very well. Markets do not follow a fixed script.
So Where Should a Beginner Invest in 2026?
For most first-time investors, building the portfolio from the large-cap side first is easier than starting heavily with small-cap funds.
That does not mean putting every rupee into large-cap funds forever.
The idea is to build the portfolio in stages.
A beginner might first understand how SIPs, NAV movements and market corrections feel. Once comfortable with equity volatility, some exposure to mid-cap companies can be added.
Small-cap exposure can come later if the investor has a long horizon and genuinely understands the additional risk.
An illustrative equity allocation could look like this:
| Investor approach | Large-cap | Mid + Small-cap |
|---|---|---|
| Conservative beginner | 80–100% | 0–20% |
| Moderate beginner | 60–75% | 25–40% |
| Aggressive long-term investor | 50–60% | 40–50% |
These percentages are only examples for understanding portfolio construction. Your actual allocation should depend on your goals, income stability, existing investments and ability to handle losses.
A beginner does not need all three categories from day one.
Should Beginners Avoid Small-Cap Funds Completely?
Not necessarily.
Small-cap funds are not “bad” investments.
The problem starts when investors buy them for the wrong reason.
For example:
“This fund gave the highest three-year return, so I will put all my SIP money into it.”
That is return chasing.
A better question is:
“If this fund falls sharply and stays weak for two years, will I still continue my SIP?”
If the answer is no, your small-cap allocation is probably too high.
Even investors in their 20s should not assume that age alone gives them high risk tolerance.
Your behaviour during a market fall matters more.
What About Mid-Cap Funds?
For many long-term investors, mid-cap can sit between the two extremes.
You get exposure to businesses that may have more growth potential than large companies without putting the entire portfolio into the smallest listed companies.
That makes mid-cap funds worth considering for goals that are several years away.
Still, mid-cap should not automatically become 70% or 80% of a beginner’s portfolio simply because recent returns look attractive.
The right amount should come from your risk tolerance, not a return chart.
SIP or Lump Sum: What Is Better for Beginners?
For salaried investors, a Systematic Investment Plan (SIP) is usually easier to manage.
Instead of trying to predict whether the market will rise or fall next month, you invest a fixed amount regularly.
For example:
₹5,000 every month instead of waiting to invest ₹60,000 at the “perfect” market level.
When markets fall, the same SIP amount buys more mutual fund units. When markets rise, it buys fewer units.
This does not remove market risk, but it helps create investing discipline.
More importantly, SIP investing reduces the temptation to constantly enter and exit the market based on news.
Don’t Choose a Fund Only by Past Returns
This is one of the most common mistakes beginners make.
A mutual fund ranking first this year may not remain number one five years later.
Before selecting a scheme, look at things such as:
- Fund category
- Investment strategy
- Expense ratio
- Portfolio concentration
- Fund manager track record
- Performance across different market phases
- Risk-adjusted returns
- Benchmark performance
Also check whether your existing funds already own many of the same stocks.
Owning five mutual funds does not automatically mean you have five different portfolios.
Do You Really Need Separate Large, Mid and Small-Cap Funds?
No.
Some beginners prefer keeping things simple.
A flexi-cap fund, for example, can invest across large-cap, mid-cap and small-cap companies. Under current SEBI rules, flexi-cap schemes must maintain at least 65% in equity and equity-related instruments, while the fund manager can move across market-cap segments.
For someone who does not want to manage three different categories, this can be an option worth studying.
Another simple route is using a broad-market or large-cap index fund as the core and adding one mid-cap allocation later.
The number of funds is less important than knowing why each fund exists in your portfolio.
What About Mutual Fund Tax in 2026?
For equity-oriented mutual funds, tax also matters when you redeem your investment.
Under the current rules, short-term capital gains covered under Section 111A are taxed at 20%, while qualifying long-term capital gains under Section 112A are taxed at 12.5% on gains exceeding ₹1.25 lakh in a financial year, subject to applicable conditions.
Tax rules can change, so investors should check the latest Income Tax Department guidance before making redemption decisions.
Tax should be considered, but it should not push you into holding a poor investment simply to avoid paying tax.
Income Tax Department – Capital Gains Tax Rules
Common Mistakes Beginners Should Avoid in 2026
One mistake is putting the entire portfolio into small-cap funds because the historical return looks high.
Another is starting too many SIPs. Three large-cap funds do not necessarily provide three times the diversification.
Also avoid checking NAV every day. Mutual funds meant for long-term goals will naturally move up and down.
And do not invest money needed soon.
Your emergency fund, next year’s school fees, home down-payment money or other short-term requirements should not depend on whether the stock market is having a good month.
SEBI Mutual Fund Riskometer Guide
A Simple Rule to Remember
Think of your equity portfolio like building a house.
Large-cap can form the foundation.
Mid-cap can provide additional growth.
Small-cap can be the higher-risk portion.
You can adjust those portions as your knowledge, income, goals and risk tolerance improve.
There is no rule saying every investor must own all three.
Which Category Is Best for Beginners in 2026?
If you are completely new to mutual funds, large-cap exposure is generally the easier starting point among these three categories.
Once you understand how equity markets behave, a controlled mid-cap allocation can be considered for additional long-term growth.
Small-cap funds are better treated as an optional part of the portfolio rather than the foundation of a beginner’s investment plan.
The biggest advantage a new investor has is not finding the next top-performing mutual fund.
It is time.
Start with an amount you can continue investing through good markets and bad ones. Keep your portfolio understandable. Increase risk only when you know why you are taking it.
Over a long investment journey, consistency often matters far more than chasing whichever category is currently giving the highest return.
FAQs
Q1. Which mutual fund is best for beginners in 2026?
Large-cap funds are generally easier for beginners because they usually have lower volatility than mid-cap and small-cap funds.
Q2. Are small-cap mutual funds risky?
Yes. Small-cap funds can offer high growth potential, but they may also see sharp falls during weak market phases.
Q3. Is mid-cap better than large-cap?
Not always. Mid-cap funds may offer higher growth potential, while large-cap funds usually provide relatively better stability.
Q4. Can beginners invest in all three categories?
Yes, but it is not necessary. Beginners can start with large-cap exposure and add mid-cap or small-cap funds gradually.
Q5. How long should I stay invested in equity mutual funds?
For equity mutual funds, a long-term approach is better. Large-cap funds may suit 5+ years, while mid-cap and small-cap funds are generally better suited for 7–10 years or more.
Further Reading
Stock Market 101 – Lesson 37: Mutual Fund Mistakes
Stock Market 101 – Lesson 35: Mutual Fund Metrics Made Simple
Stock Market 101 – Lesson 34: How to Choose a Mutual Fund
Stock Market 101 – Lesson 33: Mutual Fund Basics: Equity, Debt, Hybrid
SIP vs Lump Sum: Which Is Better for Mutual Fund Investors?
Disclaimer
This article is for educational purposes only and should not be considered investment, tax or financial advice. Mutual fund investments are subject to market risks. Read all scheme-related documents carefully and consider consulting a SEBI-registered investment adviser before making investment decisions.
Article Information
Author: Kartalks Education Desk
Reviewed by: Kartalks Editorial Team
Content Type: Mutual fund education, large-cap fund explanation, mid-cap fund explanation, small-cap fund explanation, risk comparison, beginner investing guide, asset allocation awareness, and investor education
Sources: SEBI investor education material, AMFI mutual fund resources, mutual fund scheme documents, NSE/BSE market data, official public sources, and general finance education references
Last Updated: September 12, 2026
Very useful information for people who want to start investing.
Thank you! We’re glad you found the information helpful for new investors.